High mortgage rates compound housing affordability problems
Clip: 9/28/2026 | 6m 31sVideo has Closed Captions
High mortgage rates compound housing affordability challenges
The average rate on a 30-year mortgage is back above 7% for the first time in twenty months. It’s rough news for the housing market and homebuyers already struggling with rising prices elsewhere. It comes as Treasury yields, which impact borrowing costs across the economy, hit multi-decade highs. Amna Nawaz discussed more with David Wessell of the Hutchins Center on Fiscal and Monetary Policy.
Problems playing video? | Closed Captioning Feedback
Problems playing video? | Closed Captioning Feedback
Major corporate funding for the PBS News Hour is provided by BDO, BNSF, Consumer Cellular, American Cruise Lines, and Raymond James. Funding for the PBS NewsHour Weekend is provided by...
High mortgage rates compound housing affordability problems
Clip: 9/28/2026 | 6m 31sVideo has Closed Captions
The average rate on a 30-year mortgage is back above 7% for the first time in twenty months. It’s rough news for the housing market and homebuyers already struggling with rising prices elsewhere. It comes as Treasury yields, which impact borrowing costs across the economy, hit multi-decade highs. Amna Nawaz discussed more with David Wessell of the Hutchins Center on Fiscal and Monetary Policy.
Problems playing video? | Closed Captioning Feedback
Where to Watch PBS News Hour
PBS News Hour is available to stream on pbs.org and the PBS app.
Providing Support for PBS.org
Learn Moreabout PBS online sponsorshipAMNA NAWAZ: The average rate on a 30-year mortgage is back above 7 percent for the first time in 20 months.
It's rough news for the housing market and for homebuyers already struggling with rising prices elsewhere.
And it comes as treasury yields, which impact borrowing costs across the economy, hit multidecade highs and after inflation fears forced the Federal Reserve to hike interest rates for the first time in more than three years.
To help us understand what all of this means, we're joined again by David Wessel.
He's director of the Hutchins Center on Fiscal and Monetary Policy at the Brookings Institution.
David, always good to see you.
DAVID WESSEL, Brookings Institution: Good to be here.
AMNA NAWAZ: Before we turn to the bond market, the average 30-year fixed-rate mortgage currently sits at 7.03 percent, according to Freddie Mac.
What does the rate going above 7 percent mean for homebuyers and the housing market?
DAVID WESSEL: Right.
Well, actually today, according to Bankrate, which is the daily thing, it's up to 7.2 percent today.
A year ago, it was 6.3 percent.
So on a mortgage of $250,000, that's an extra $1,800 a year in payments.
It's like having a 13th month of mortgage payments.
So it's a big deal.
And what it means is that, A, houses will be more expensive.
So, many people will be priced out of the market.
You need to have more income to support that.
And, secondly, it means -- and we have seen this from a number of the big homebuilders, Pulte, Lennar, D.R.
Horton -- they are anticipating less demand so they're going to build fewer houses, which, of course, is not what we need now at a time when we know we need more houses.
AMNA NAWAZ: Let me ask you about the bond market now.
It's been getting a lot of attention.
Help our viewers understand, what exactly is the bond market, why does it matter, and why so much anxiety around it in recent months?
DAVID WESSEL: Well, the -- when we talk about mortgage rates, why do mortgage rates move?
They move because they're pegged to what happens in the bond market.
And the bond market is a big financial market.
There's $32 trillion worth of U.S.
Treasury debt in the bond market.
That's about the same size as all the stocks on the New York Stock Exchange, and then, if you add in corporate borrowing or state and local governments, another $16 billion.
So -- $16 trillion.
So, what this means is that people are buying and selling Treasury bonds.
They're driving up the yield because there's so much more borrowing in the economy.
And unlike the stock market, which matters if you own stock, the bond market yields affect our borrowing rates, not only mortgages, but it affects what you pay for an auto loan.
And it affects what the government has to pay to borrow.
And the federal government in particular borrows a lot of money.
So when rates go up, the Treasury has to pay more to borrow.
Eventually, that widens the deficit and eventually that will mean higher taxes.
AMNA NAWAZ: So, the yields on 10-year Treasury bonds, for example, hit 5.2 percent today.
That's the highest we have seen since January of 2002.
DAVID WESSEL: Right.
AMNA NAWAZ: You mentioned borrowing.
Is that the sole driver behind those rising rates?
DAVID WESSEL: Well, there's a supply and demand thing.
So the supply of borrowing is how much money the Treasury borrows, and the demand is how much investors are willing to pay for it.
And what's happened is, the Treasury is borrowing more and more because we're running big deficits.
And now there's a new player.
All these hyperscalers are borrowing a lot at long maturities, 10-year, 20-year, 30 years.
And that used to be the place where the -- where the Treasury had -- didn't have much competition.
So what's happened is, we have a strong economy.
People in the markets expect the Fed to keep raising interest rates, and the bond market responds to what future interest rates will be.
You have more concerns about inflation being persistent because of what's going on in the Middle East.
You have these new borrowers and the hyperscalers.
And on top... AMNA NAWAZ: Hyperscalers are the AI data centers too.
DAVID WESSEL: Hyperscalers, Amazon, Meta, Google, and stuff like that.
So -- and at the same time, there's a little bit of anxiety in the market about the credibility of the U.S.
government.
Will we get our budget deficit under control?
Will the government function?
I think there's a lot more confidence in the Federal Reserve now because of what Kevin Warsh did recently raising interest rates.
But it used to be the Treasury could borrow at rates cheaper than everybody else.
The economists call it the convenience yield, and that's eroded over time, which is a bad sign.
AMNA NAWAZ: So, for the American consumer, big picture, they have got higher prices for gas, for groceries, health care.
The cost of living is going up.
We have heard the president repeatedly boast about this being the greatest economy in history and also saying that all of these disruptions are short-term, that this pain and the higher costs are temporary.
Are there any signs to back that up?
DAVID WESSEL: Well, first of all, the president has a tendency to hyperbole, and this is a good instance.
The economy has been pretty good, surprisingly resilient.
Unemployment by historical standards is pretty low.
The problem has been inflation, which is why the Fed is raising interest rates.
The one thing that could end -- but part of this is the president's fault.
Tariffs have pushed up inflation, and the war in Iran has definitely pushed up inflation.
So you tell me what the president is going to do on tariffs, you tell me whether the president is going to find a way to end the war in Iran and bring down oil prices, you tell me whether the president and his Treasury secretary actually have a plan to reduce the federal deficit, and I will tell you when interest rates are going to go down.
AMNA NAWAZ: Dare I ask you how high you think mortgage rates could potentially go?
Already at 7 percent.
DAVID WESSEL: I have no idea.
DAVID WESSEL: But, look, they have gone up quite a bit.
What will happen is, this will be like a brake on the economy, B-R-A-K-E.
And if it slows the economy some, that will take some pressure off of prices and take some pressure off of the inflation.
But, for now, we just have -- the economy is doing pretty well, and there's a lot of demand for money, a lot of demand for borrowing, and that's pushing it up.
AMNA NAWAZ: Always appreciate you telling us everything you know and what we don't yet know.
DAVID WESSEL: Happy to tell you what I don't know.
AMNA NAWAZ: David Wessel, always great to see you.
Thank you so much.
DAVID WESSEL: You're welcome.
 New
Blanche shatters DOJ standard of political independence
Video has Closed Captions
How Blanche is shattering DOJ's standard of political independence (5m 27s)
 New
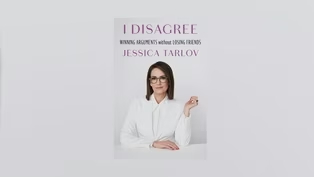
Jessica Tarlov on her new book, 'I Disagree'
Video has Closed Captions
Jessica Tarlov on navigating political differences and her new book, 'I Disagree' (8m 9s)
 New
News Wrap: UK investigating possible plot against U.S. base
Video has Closed Captions
News Wrap: UK police investigating possible plot targeting U.S. base (5m 19s)
 New
Powerful nor’easter batters parts of East Coast
Video has Closed Captions
Powerful nor’easter batters parts of East Coast (2m 52s)
 New
Tamara Keith and Amy Walter on TV ads promoting Trump
Video has Closed Captions
Tamara Keith and Amy Walter on taxpayer funds used for TV ads promoting Trump (10m 14s)
 New
WFP official on addressing hunger in face of wars, disasters
Video has Closed Captions
WFP official on addressing global hunger in face of wars and climate disasters (7m 28s)
 New
What Trump's fuel economy rollback means for drivers
Video has Closed Captions
What Trump's rollback of fuel economy standards means for drivers (6m 18s)
Providing Support for PBS.org
Learn Moreabout PBS online sponsorship New Episode
- News and Public Affairs
Today's top journalists discuss Washington's current political events and public affairs.
 New Episode
- News and Public Affairs
FRONTLINE is investigative journalism that questions, explains and changes our world.
 New Episode
 New Episode
 New Episode
 New Episode
 New Episode
 New Episode
 New Episode
 New Episode
 New Episode
Support for PBS provided by:
Major corporate funding for the PBS News Hour is provided by BDO, BNSF, Consumer Cellular, American Cruise Lines, and Raymond James. Funding for the PBS NewsHour Weekend is provided by...